Table of Contents
Compound V3 USDC on Ethereum is paying 6.87% base yield as of 8 October 2026, the highest rate among established stablecoin lending protocols this week. That is 2.88 percentage points above Aave V3 USDC and carries $34 million in total value locked after 1,456 days of operational history. Four new venues entered the dataset this week, including Jupiter on Solana and a Uniswap V3 BTC-USDT pool showing 25.54% yield with full impermanent loss risk.
Stablecoin Yields
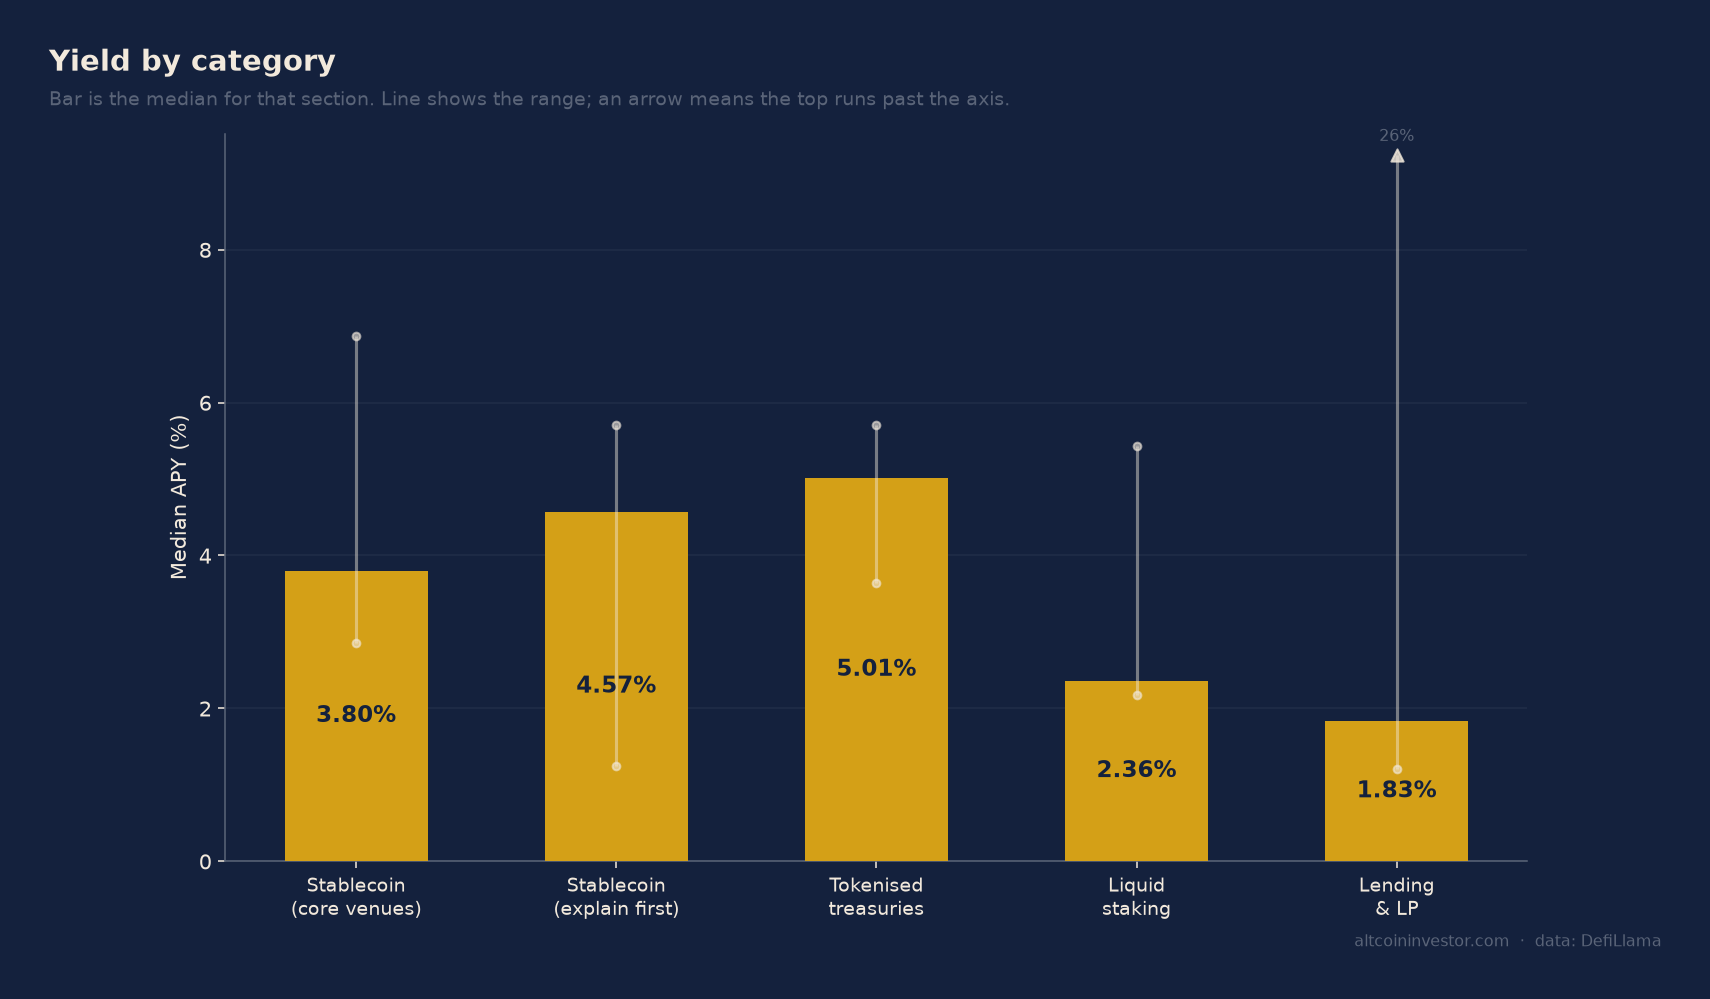
The core stablecoin lending venues as of 8 October 2026 are clustered between 3.72% and 6.87%. Sky Lending SUSDS on Ethereum and Arbitrum is paying 3.8% across $5,278 million in TVL, backed by 594 days of history. Spark Savings offers 3.75% on USDT, 3.8% on USDS, and 3.8% on USDC across Ethereum, Arbitrum, and Base. Aave V3 USDC is at 3.99% across Ethereum, Arbitrum, Base, and Polygon with $251 million deposited. Aave V3 USDT on Ethereum sits at 3.72% with $227 million TVL. Aave V3 SGHO on Ethereum offers 4.5% with $173 million locked and 145 days of operational data.
Sparklend DAI on Ethereum pays 2.85% with $75 million TVL and 844 days of history. The outlier is Compound V3 USDC on Ethereum at 6.87%, though it carries only $34 million in deposits. Compound V3 USDT on Ethereum is at 3.23% with $17 million TVL.
Several stablecoin venues require mechanism disclosure. Ethena sUSDe on Ethereum is paying 5.44% with $1,223 million TVL. That yield is funding-rate dependent and can go negative in a bear market. Sparklend USDS on Ethereum offers 4.57%, but 100% of that APY comes from reward token emissions rather than protocol revenue, with $983 million deposited. Morpho Blue vaults GTUSDCP and STEAKUSDC on Base and Ethereum are both at 4.42% with $708 million and $584 million TVL respectively. Risk parameters in Morpho vaults are set by the curator, not the protocol.
Jupiter Lend USDC on Solana is paying 4.15%, composed of 3.81% base and 0.34% rewards, with $534 million locked. Solana carries a different chain risk profile to Ethereum. Fluid Lending USDC across Ethereum, Arbitrum, and Base is at 5.71% with $202 million TVL. Fluid is a newer lending design with a shorter track record than Aave. Sky Lending sDAI on Ethereum pays 1.25% with $201 million TVL and 1,399 days of history. Sky Lending USDS on Ethereum offers 5.62%, entirely from emissions, with $165 million deposited.
Tokenised Treasuries And Credit
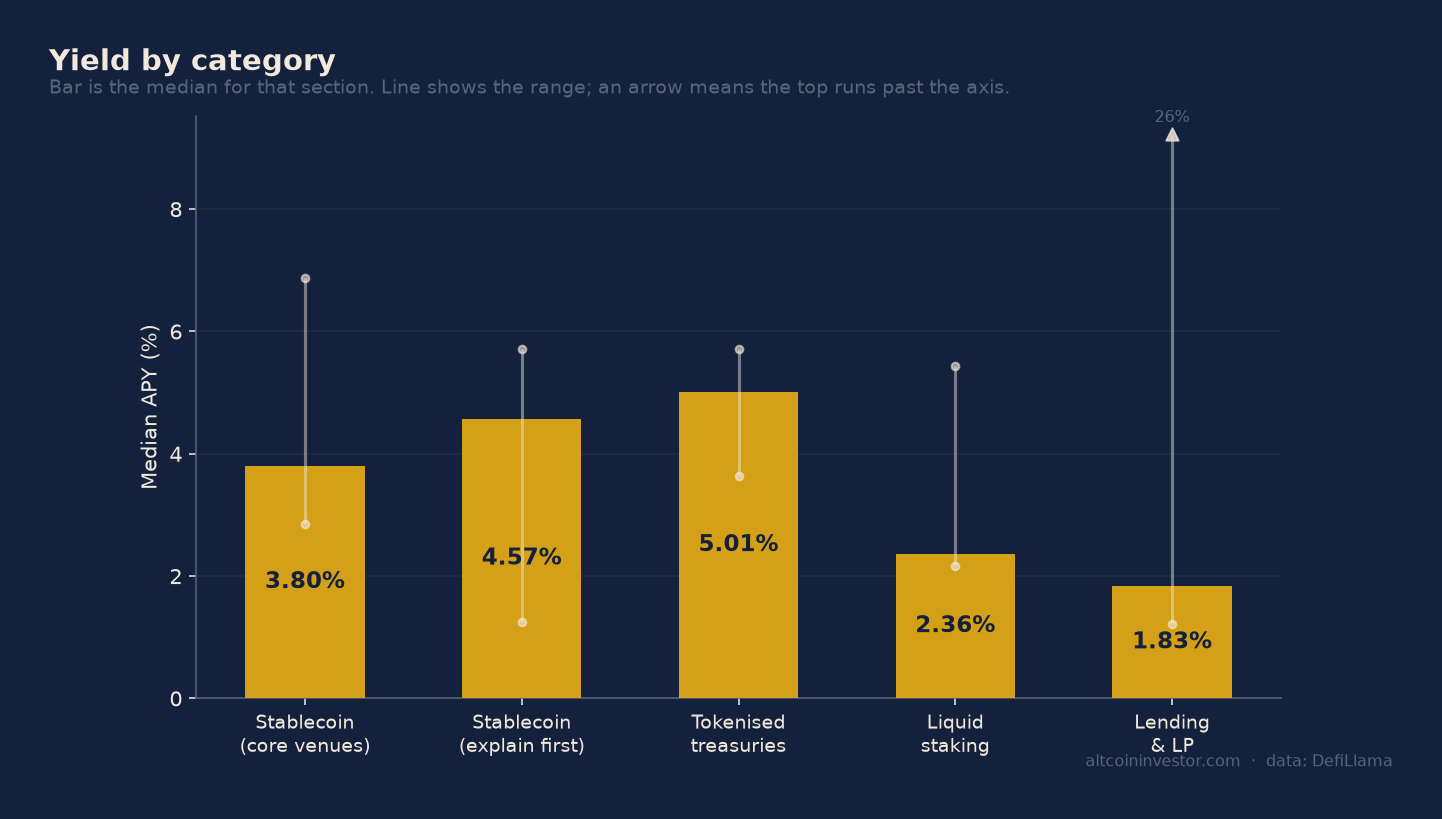
Tokenised US Treasuries and institutional credit products carry counterparty and regulatory risk rather than smart-contract risk. Maple USDC on Ethereum is paying 5.21% with $2,768 million in TVL and 437 days of operational history. That yield comes from institutional credit and carries real borrower default risk. Maple USDT is at 5.46% with $637 million TVL under the same default risk profile. Maple USDG is paying 5.01% with $484 million locked.
Ondo USDY on Ethereum and Solana offers 3.64% with $1,400 million in TVL. This is a tokenised US Treasury product from Ondo. BlackRock BUIDL on Solana and Ethereum pays 3.78% with $1,374 million TVL and 195 days of history, representing tokenised US Treasuries from BlackRock. Invesco USTB on Ethereum is at 3.93% with $597 million locked and 188 days of operational data, another tokenised Treasury vehicle.
Usual USD0 bUSD0 on Ethereum is paying 5.71% with $504 million TVL, but 100% of that APY comes from reward emissions. This is a treasury-backed product with a token incentive layer. Centrifuge USDS on Ethereum offers 3.96% with $326 million TVL, representing tokenised real-world credit with 141 days of history.
Liquid Staking
Ethereum liquid staking yields as of 8 October 2026 sit between 2.17% and 2.36%. Lido stETH is at 2.24% with $24,386 million in TVL and 1,587 days of operational history. Binance Staked ETH wBETH is paying 2.22% with $8,859 million locked. This is an exchange-operated product carrying custodial counterparty risk. Ether.fi weETH on Ethereum and Base offers 2.27% with $5,626 million TVL. This product includes restaking exposure on top of base staking yield.
Rocket Pool rETH on Ethereum pays 2.17% with $1,312 million in TVL and 1,358 days of history. Coinbase Wrapped Staked ETH cbETH is at 2.36% with $478 million locked. StakeWise V3 osETH on Ethereum offers 2.3% with $395 million TVL, a smaller ETH staking pool with a longer track record of 1,016 days.
Solana liquid staking rates are structurally higher because Solana validator yields include MEV and higher base staking returns. Jupiter Staked SOL jupSOL is paying 5.43% with $581 million in TVL. Jito jitoSOL offers 4.82% with $1,164 million locked, explicitly including MEV rewards. Drift Staked SOL dSOL is at 4.96% with $312 million TVL. Marinade msol pays 4.74% with $252 million in deposits.
What Changed
Four venues entered the dataset this week. Jupiter Lend USDC on Solana appeared at 4.15%, Sky Lending USDS on Ethereum at 5.62%, Jupiter Lend WSOL at 4.3%, and Uniswap V3 WBTC-USDT at 25.54%. Four pools dropped out of the dataset: Fluid Lending USDT at 4.29%, Pendle V2 USDAI at 2.33%, Spark Savings ETH at 1.55%, and Curve dex oETH-WETH at 1.62%.
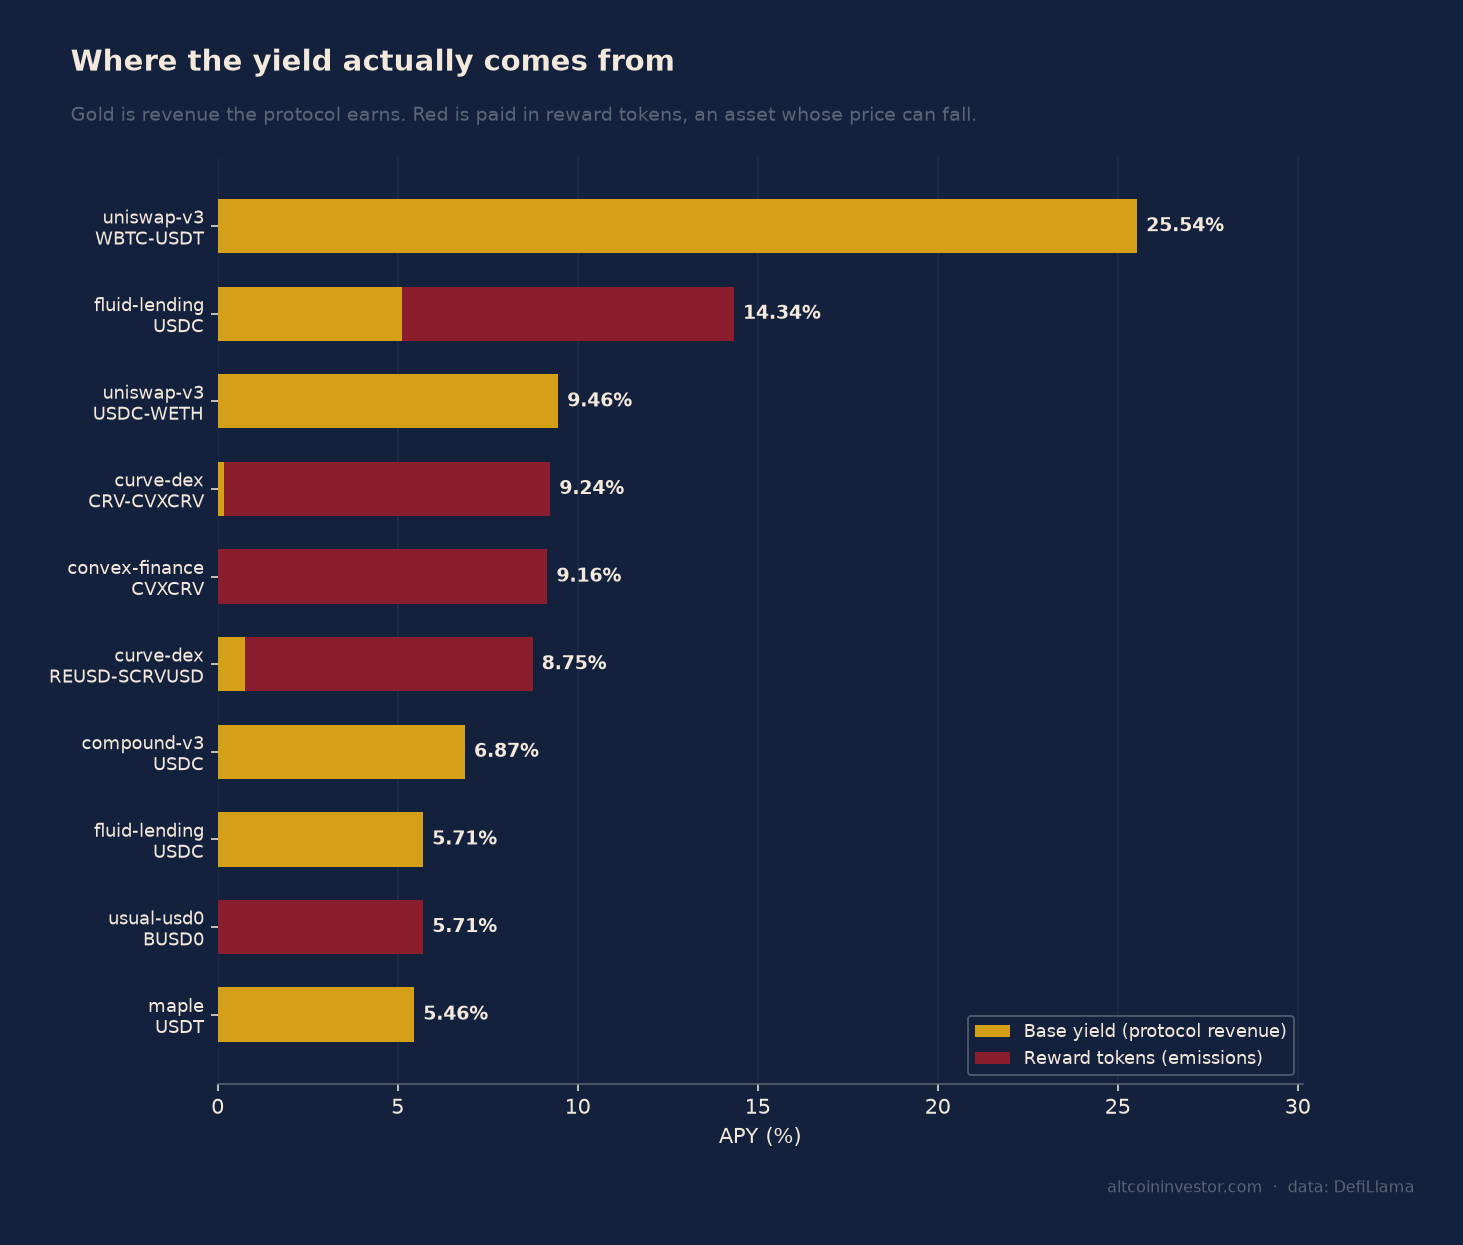
The largest movement was Curve dex crvUSD-cbBTC falling from 10.58% to 1.21%, a drop of 9.37 percentage points. Fluid Lending USDC on Base jumped from 8.8% to 14.34%, though 64% of that APY is now emissions rather than base yield. Uniswap V3 USDC-WETH rose from 7.15% to 9.46%. Convex Finance cvxCRV fell from 10.8% to 9.16%. Fluid Lending USDC across Ethereum, Arbitrum, and Base rose from 4.67% to 5.71%. Marinade msol dropped from 5.77% to 4.74%.
Where The Yield Is Not Real
A pool paying 4% in protocol fees and 18% in a reward token down 60% is not an 18% pool. The emissions-dependent venues as of 8 October 2026 are paying headline APYs that are mostly or entirely reward tokens rather than sustainable protocol revenue.
Fluid Lending USDC on Base is showing 14.34%, but 9.22 percentage points of that, 64% of the total, comes from token rewards. The base yield is 5.12%. Curve dex CRV-cvxCRV on Ethereum advertises 9.24%, but 9.05 percentage points, 98% of the APY, is emissions. The base yield is 0.19%. Convex Finance cvxCRV pays 9.16%, entirely from rewards with zero base yield.
Curve dex reUSD-scrvUSD on Ethereum shows 8.75%, of which 7.98 percentage points, 91%, is emissions. Usual USD0 bUSD0 on Ethereum offers 5.71%, 100% from rewards. Sky Lending USDS on Ethereum is at 5.62%, also 100% emissions. Aave V3 rLUSD on Ethereum pays 4.99%, of which 3.29 percentage points, 66%, is token rewards. Aave V3 WETH on Ethereum shows 4.82%, with 3.48 percentage points, 72%, from emissions.
These pools may be suitable for short-term liquidity mining strategies with full knowledge of token price risk and vesting schedules. They are not comparable to base-yield stablecoin lending or liquid staking products.
How To Verify Any Of This
Every venue in this report links directly to its DefiLlama pool page. Compound V3 USDC, Sky Lending SUSDS, Aave V3 USDC, Maple USDC, Invesco USTB, and Lido stETH can all be checked in one click. Yields change daily. The figures in this report are a snapshot as of 8 October 2026. Check the current APY, TVL, and pool history before deploying capital. The verification links are not decorative. They are how you confirm that the numbers are real and that the risk disclosures match the mechanism.